100 of ideas for investing. Idea #10. Investing in Bid Corporation Limited

Bid Corporation (JSE: BID), a leading international distributor of food products for the foodservice sector, is a unique South African company with operations primarily in Europe, Asia and Australia. Consequently, investing in this firm means investing in an overseas business with strong geographical diversification. For many, this has been the primary rationale for investing in Bid Corporation; however, the company offers more than just geographical diversification. It represents a reliable and profitable business within the food supply and services sector - an industry that is relatively insulated from the impacts of geopolitics and oil prices.
About Bid Corporation Limited
Bidcorp originated from the Bidvest Group, which was founded by Brian Joffe in 1988. In 2016, Bidvest’s food service business was spun off into an independent company and listed separately on the JSE. The year 2026 marks the 10th anniversary of this spin-off. Brian Joffe remains the Chairman of the Board, while Bernard Berson has served as CEO since 2016. Today, it is the largest foodservice group outside the United States, boasting the most geographically diverse footprint in the industry. The group operates in 31 countries and employs approximately 31,000 people. Its core brands include Bidfood (offering a wide range of products) and Bidfresh (supplying fresh produce to chefs). The British division of Bidfood traces its history back to 1929.
Evaluation of the idea to invest in the Bid Corporation Limited
Foodservice distribution functions as a "wholesale kitchen" for restaurants, hotels, catering businesses, hospitals, schools, and canteens. Companies in this sector source meat, fish, produce, dairy, groceries, beverages, and supplies from manufacturers, then deliver these items to professional kitchens, often on a daily basis and in smaller, frequent shipments. From an investor’s perspective, the sector has three defining characteristics:
- Resilient demand. People continue to dine out even during economic downturns. While spending may shift toward more affordable establishments, the overall volume of procurement remains stable.
- Low margins combined with high turnover. Operating margins typically hover in the low single digits. Profitability is driven by scale, efficient logistics, and strict cost discipline; consequently, large players with dense warehouse networks hold a competitive advantage.
- Consolidation through bolt-on acquisitions. The market is highly fragmented, consisting of numerous regional distributors; industry leaders grow by acquiring these smaller entities one by one.
For investors on the JSE (Johannesburg Stock Exchange), this sector is particularly attractive because nearly all of Bidcorp’s business is conducted outside of South Africa. Around 95% of the group’s operations are international. As a result, the stock is traditionally viewed as a "rand hedge" - a defensive asset denominated in South African rand that generates earnings in British pounds, euros, and Australian dollars. Investment assessment: This sector is well-suited for the conservative portion of a portfolio. While explosive growth is unlikely, the predictability of revenue and cash flow is higher than the market average.
Bid Corporation's dividend policy
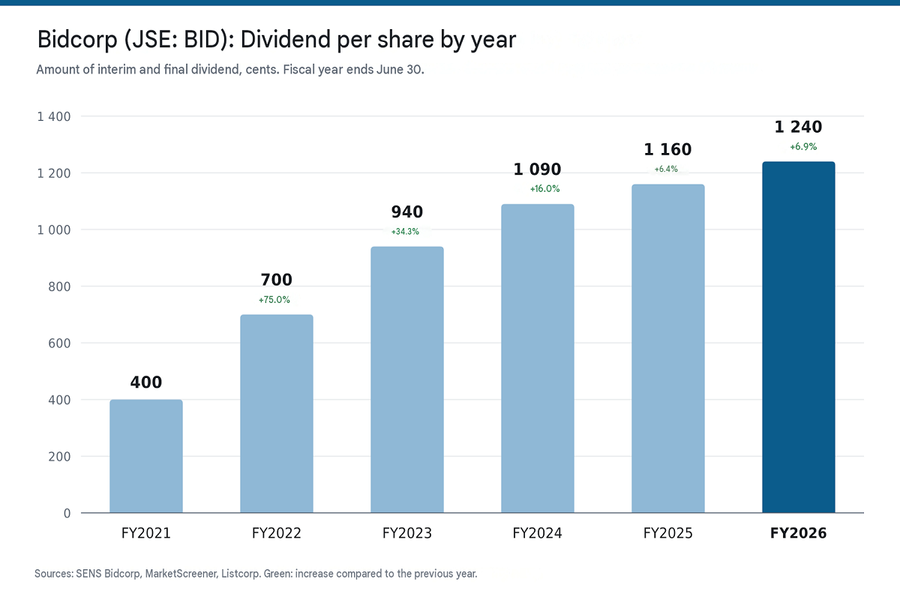
Bidcorp maintains a prudent and stable dividend policy, with payouts occurring twice a year (interim and final). The dividend yield is approximately 2.7%–2.8%. Regarding dividend growth, total dividends for FY2026 reached 1,240 South African cents (ZAc) per share, representing a year-on-year increase of 6.9%. The payout ratio stands at around 45–50% of adjusted net profit (HEPS), leaving sufficient free cash flow for mergers and acquisitions (M&A) and share buybacks. As for its buyback program, the company allocated an additional R1.1 billion toward share repurchases in FY2026.
From the standpoint of practicality, buying these shares solely for the sake of dividends makes little sense, as the yield is lower than the inflation rate and also lower than the return on bank deposits.
Fundamental and technical review
In recent years, organic growth has hovered around 5% in constant currency, supplemented by an additional 1–1.5 percentage points from acquisitions. With food inflation near zero, revenue growth is driven by volume and new customers rather than price increases. The three-year consensus forecast (according to S&P Global) projects revenue growth of approximately 4.8% and earnings per share (EPS) growth of about 6.8% per annum.
The P/E based on HEPS is around 16.5x, and the forward P/E is approximately 15.5x, which is in line with the average among peers.
Most analysts view investments in this company favorably, and forecasts suggest its shares could rise by up to 14% over the next 12 months - a growth rate roughly double the current one.
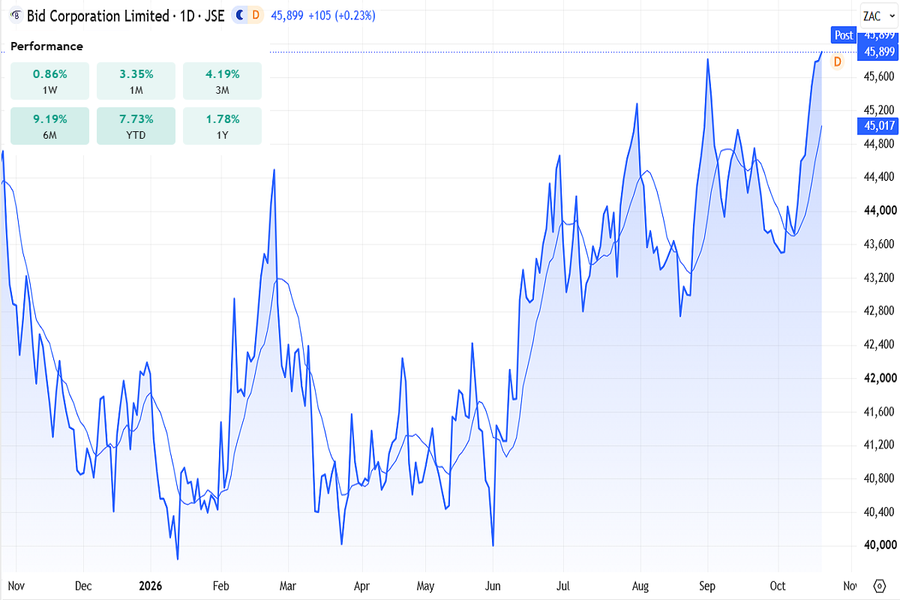
BID Corp stocks on JSE, October 2026
Currently, the shares are trading within an upward trend that has persisted for the last seven months. During this period, the price got close to its highest level since the stock’s listing in 2016, though it has not yet set a new record. Forecasts suggest that surpassing these all-time highs is possible in the foreseeable future; the price needs to rise by just 3–5% to test and break through these peaks while according to forecast stocks can add up to 14%. Technical analysis indicators support the analysts' assessments and are currently signaling a " Strong buy." No overbought zone and no signs of trend reversal. So everything is possible here.
SWOT point of view on the Bid Corporation stocks
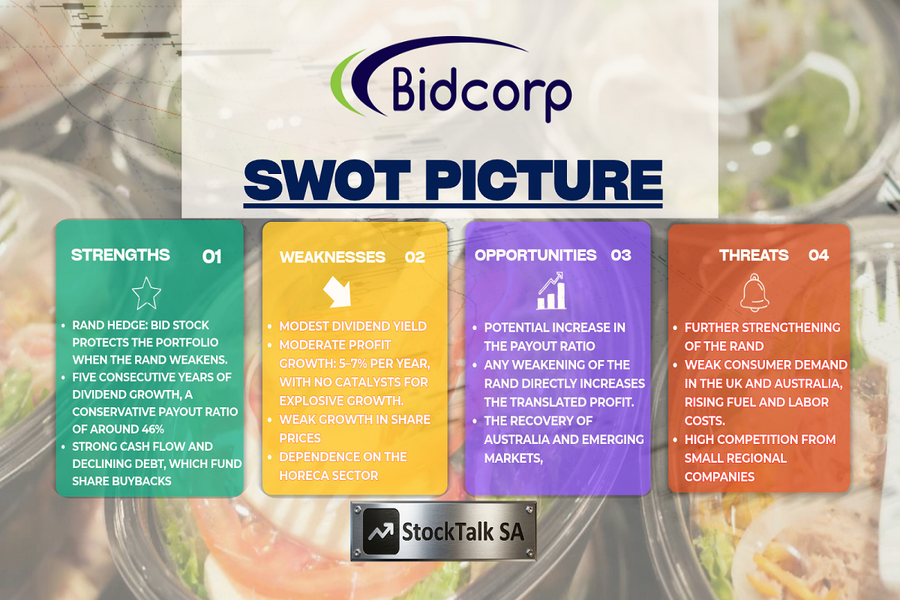
SWOT of investments in the BID Corp
BID is a classic "buy-and-forget" stock: a high-quality, well-managed business with a strong balance sheet and solid cash flow, albeit with modest growth and returns. The primary paradox currently surrounding the stock is that while the business continues to grow steadily in constant currency terms, its price in South African rand (ZAR) has remained stagnant for three years - a result of a strong rand and multiple compression. Consequently, shareholder returns in the coming years will be driven less by operational performance (which is predictable) and more by the rand’s exchange rate and whether the market restores the stock’s former valuation premium. Bullish scenario: The rand stabilizes or weakens; share buybacks boost earnings per share (EPS) by FY2027; the European segment maintains double-digit growth; and the Australian business recovers. The valuation multiple expands back to 17–18x forward earnings, pushing the share price above R458 toward the R474–512 range, aligning with the current consensus analyst price target. Including dividends, this would yield a total annual return of approximately 15–17%. This is a scenario, not a forecast. Bearish scenario: The rand strengthens beyond R16 to the US dollar; consumer demand in the UK and Australia weakens; and geopolitical pressures weigh on emerging markets. Growth in rand terms slows to the low single digits, the market continues to compress the valuation multiple, and the share price retreats toward its 200-day moving average (around R424)—or, in the event of a broader "risk-off" sentiment on the JSE, toward its annual low of approximately R395. Dividends would likely remain intact, however, which should limit the downside. This is a scenario, not a forecast.
Summary
Bid Corporation Limited (BID) is a high-quality "defensive growth" stock listed on the JSE. It offers investors a unique combination: a currency hedge through international revenue, a stable dividend yield (~2.8%), and strong management that generates double-digit growth in free cash flow.
- Investment thesis: Acquiring a robust global foodservice business using the South African rand.
- Target investor profile: A conservative-to-moderate portfolio focused on long-term capital appreciation, complemented by moderate dividend payouts.
The key difference compared to many other stocks is the absence of rallies where prices might surge by tens of percent in a single month as well as the absence of severe drawdowns; instead, there is inherent stability and growth potential. This is further supported by positive ratings and forecasts, coming not only from subjective expert opinions but also from technical indicators. All of this offers one undeniable advantage: this is not a stock for which you need to wait for a "sale" or a specific entry price. It is a stock you can purchase whenever you wish, without having to worry that the trade might turn into a loss right next day because someone in the U.S decided to rise interest rate or PMI is below forecasts. Reaction on all factors will be as moderate as possible.

Stan Lytynsky
Stan Lytynsky is a well known financial expert with more than 1000 of market reviews. For the last 10 years he wrote reviews for different blogs and websites. In particular he worked for SuperForex and Zetradex forex brokers as a market analyst. Currently he is living in Canada and focused on the African market as the most promising and growing.
Comments
Loading comments…
Log in or sign up free to join the discussion.