JSE & Global Markets Digest. October 2026, week 3


This week, stock markets came under pressure from a confluence of factors, ranging from geopolitics and a rally in oil prices to persistent skepticism about the AI sector and its high costs. Monetary policy tightening also remains on the radar and is set to become a more prominent factor in the near future. Some companies still managed to grow in these conditions, but they would likely have achieved even more without this “perfect storm” around them. Let’s look at how investors reacted, and which stocks still earned their trust.
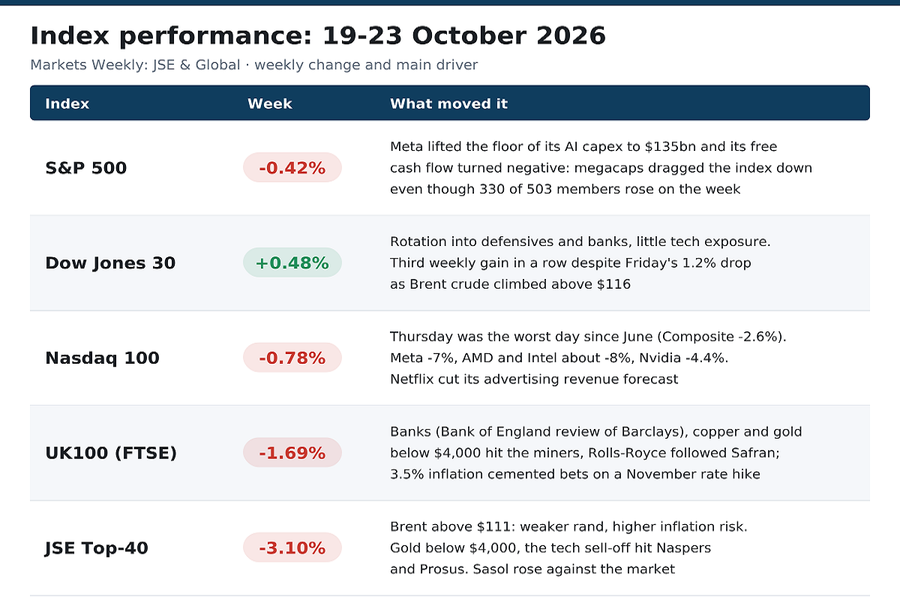
Indices comparison
JSE market in October 2026, week 3
After a strong previous week, the JSE suffered one of its worst weeks in months. Every risk imaginable landed on South African stocks at once: from the standoff in the Strait of Hormuz, which drove oil to multi-month highs, to fears over Big Tech’s enormous AI spending, which weighed on Naspers and Prosus. Even Famous Brands blamed geopolitics, although Debonairs pizza and Steers burgers are a long way from the Strait of Hormuz. But expensive oil means expensive fuel, costly logistics and a poorer customer. In these conditions, only one sector, or rather one company, is thriving: Sasol.
This way, Sasol is our Rally of the week number 1 with +13.86% growth. For context: by early October Sasol had delivered a dollar return of almost 120% in 2026, making it the best-performing emerging-market stock outside Asia. The secret is its business model. Sasol makes fuel from coal rather than crude oil, so its feedstock does not get more expensive when the oil price rises, while its products do.
Sasol benefited from two drivers at once. The first was oil: Brent hit a five-month high on Tuesday. The second was its first-quarter FY2027 operational update, published on Wednesday, 21 October:
- The company benefited from higher prices and supportive refining margins.
- Mining output reached its highest quarterly level in six years, reducing the need to buy coal externally.
- Full-year guidance was reaffirmed.
- Buyback program isn't excluded
The update was not flawless: production at Secunda and the Natref refinery fell from the previous quarter, but liquid fuel sales volumes rose.
One more positive news on JSE is a strong financial report, published by the Karooooo ltd. The owner of vehicle tracking business Cartrack reported results for the quarter to 31 August 2026.
According to the report, Revenue rose 22% to R1.64 billion, and operating profit increased 19% to a record R422 million. In South Africa, subscription revenue growth accelerated for the seventh quarter in a row, reaching 25%. Earnings per share rose 18%, and the FY2027 outlook was reaffirmed. Higher taxes and finance costs slightly held back profit growth but seems they deal with it.
JSE TOP-40 index tech review
The JSE Top-40 fell 3.10% and closed the week below the psychological 100,000 mark. For South Africa, which imports most of its fuel, high oil prices means a weaker rand and a new round of inflation: the regulated petrol price rose about 5% in September and about 12% in October.
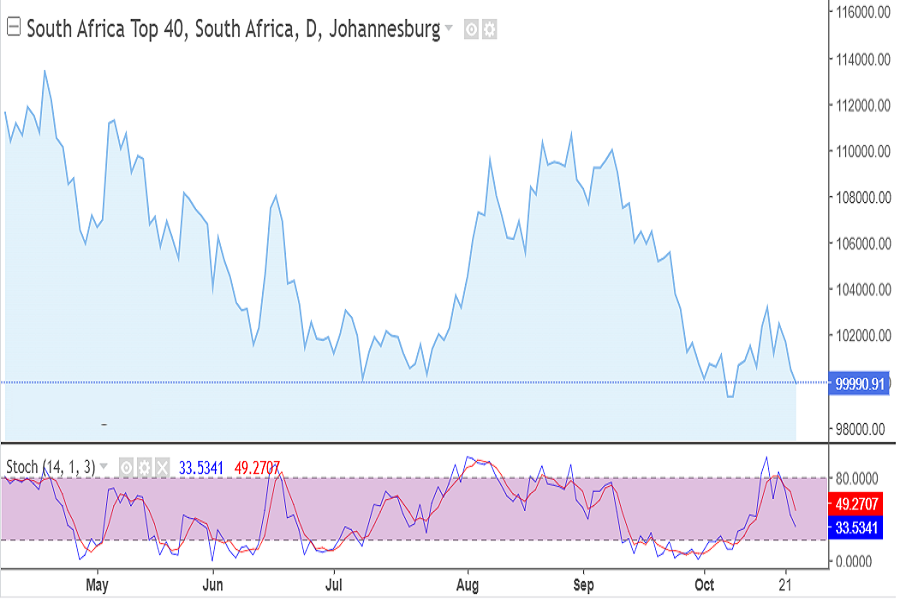
The current situation aligns with our forecast and the downward trend on the chart. Given all the circumstances and the fact that the market is not in an oversold state, there is every reason to expect further decline in the near term. Strong Sell signal from the most of tech indicators confirm expectations.
UK stock market in the third week of October 2026
London gave back more than half of the previous week’s gains. The damage started on Monday, when the Financial Times reported that the Bank of England was checking whether Barclays traders had made hard-to-sell loans look safer than they were. Barclays fell 3.5% and the FTSE 100 lost 1.1% that day, and on Thursday Barclays’ third-quarter results disappointed. September inflation came in at 3.5%, above the 3.4% forecast, while unemployment fell to 4.7%. Markets now fully price a rate hike on 5 November, which would be the Bank of England’s first in more than three years.
Ashtead Technology Holdings (AIM), +17.14% is the main winner of the week on LSE with their on driver. A UK supplier of subsea equipment for the offshore energy industry, renting out equipment and providing technology solutions for offshore oil and gas fields and wind farms finally confirmed their possible takeover offer from New York-based private equity firm Ember Infrastructure Management. Last month AIM stocks took investor's attention due to rumors and it's confirmed officially.
The board unanimously recommends the offer, arguing that amid geopolitical uncertainty and limited access to capital for acquisitions it offers shareholders a better risk-adjusted return than going it alone. Completion is expected in late Q4 2026 or early Q1 2027, after which the company will leave the stock market.
Fresnillo plc is on another side of the top with a status of the main crash on the market this week. Fresnillo stocks lost 14.5% in value, being the one of many mining companies which were losing its value on the stock exchange.
The world’s largest producer of primary silver and one of Mexico’s largest gold producers published a weak third-quarter production report. Silver output fell 11.6% year on year to 10.3 million ounces, below consensus of about 11.1 million. Gold output was 135,053 ounces, down 10.7% but in line with expectations. The reasons: lower ore grades at several mines, a 25.8% fall in silver output at the Juanicipio mine and extra maintenance on a damaged mill at the Herradura gold mine, where output fell 16.4%.
The second blow came on Friday, when gold fell below $4,000 an ounce for the first time in three months. Fresnillo lost 6% on the day, closing at 2,309 pence. A miner with falling output in a week when the metal itself got cheaper proved the most vulnerable stock in the sector.
UK100 index - fast tech review
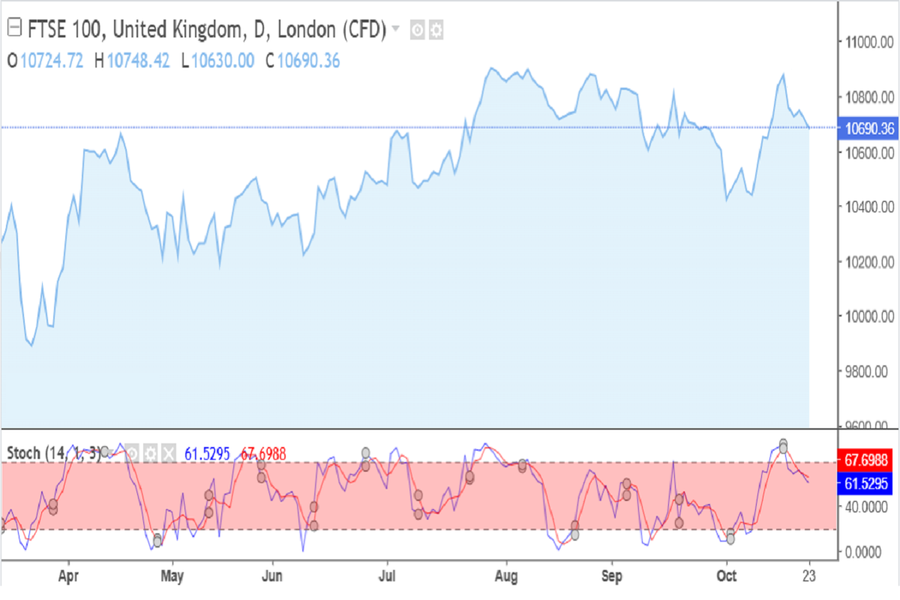
The index has ceased reaching new highs since July 2026, and this increasingly looks like a trend reversal. The coming weeks will be decisive for this chart. Further declines, accompanied by a shift in the support line, could finally confirm a trend reversal, whereas a test of the highs and the setting of new ones would refute it. The first scenario certainly appears more likely. Tech indicators looks confused. If you look at the chart you could be confused too but look at the Stochastic oscilator. It's forwarded downward and show us further direction.
US Market on the third week of October 2026
The week’s turning point came on Thursday. Meta reported record quarterly revenue of $64.6 billion, up 26%, but raised the floor of its 2026 capital spending outlook to $135-145 billion, and its free cash flow turned negative at minus $2.12 billion. Meta fell 7% and the Nasdaq Composite lost 2.6%, its worst day since June.
It wasn't the only negative event. Raising oil meand higher inflation and of course financial sector together with tech sectors remain in the red zone. Nevertheless US indices are quite stable and didn't lose more than 1%. DJI even managed to stay above 0.
Who managed to win in such a hard week? Veradermics (NYSE: MANE) with +21.73% growth. A US biotech focused on hair loss treatments, listed only in February 2026, with a market value of about $5.8 billion. On Monday, October 19, the company published the results of a Phase 3 clinical trial involving 536 men. The hair-loss drug met all primary and secondary endpoints. No serious adverse events related to the medication nor any cardiovascular-related adverse events were observed.
Stocks rose for 4 out of 5 trading days, and that was enough to place them among the top gainers in the stock market.
Hasbro (Nasdaq: HAS) is the main gainer in Nasdaq. Their stocks added +18.9% for 4 trading days of 5. One of the world’s largest toy and game makers, behind Monopoly, Transformers, NERF, Play-Doh, Dungeons & Dragons and the collectible card game Magic: The Gathering. Magic is now the main engine of Hasbro’s profits.
On Tuesday, 20 October, Hasbro reported third-quarter results and the shares jumped 11% on the day. According to the report Revenue rose 15%. Adjusted earnings per share jumped 73%. Hasbro raised its 2026 revenue growth outlook to 7-9% from 5-7% and doubled its share buyback target.
Faller of the week: Comfort Systems USA (NYSE: FIX), -19.3%.
A US contractor for building systems: heating, ventilation, air conditioning and electrical work for commercial, industrial and institutional buildings, operating in 155 US cities, is considered as a beneficiary of the data centre construction boom. But AI-related stocks are under pressure. Even quite good financial report didn't help. Additional negative factor for the company is the retirement of long-serving CFO Bill George and the absence of 2027 earnings guidance triggered a second wave of selling on Friday.
US indices tech overview
S&P500 index
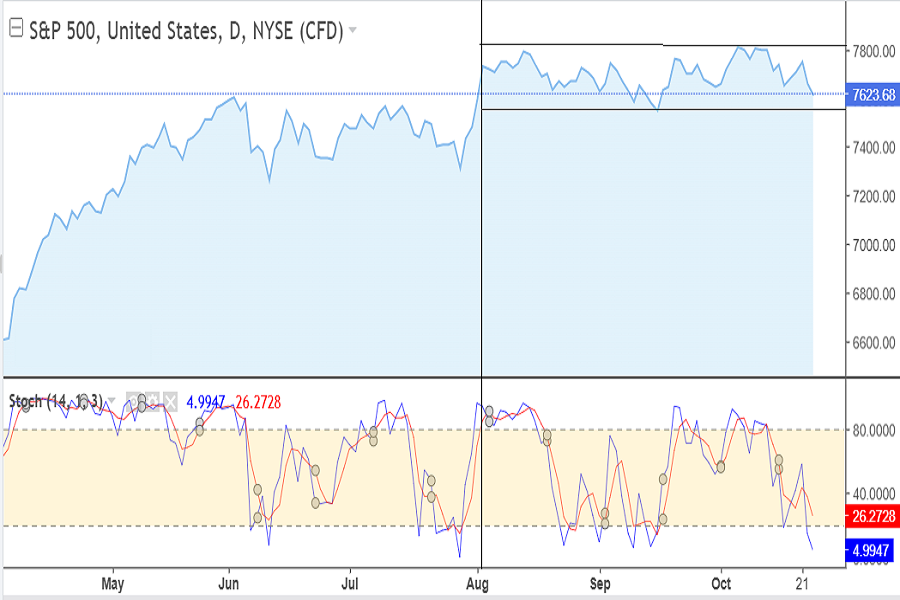
This index is hopelessly stuck in a sideways trend. If you have access to the server, please restart it. A test of support levels is possible in the near future. An increase in volatility is also likely in November, as the upcoming U.S. elections could stir up the stock market. However, if we rely solely on technical analysis, the technical indicators confirm our forecast that the support line can be tested in the near future.
2. DJI tech review
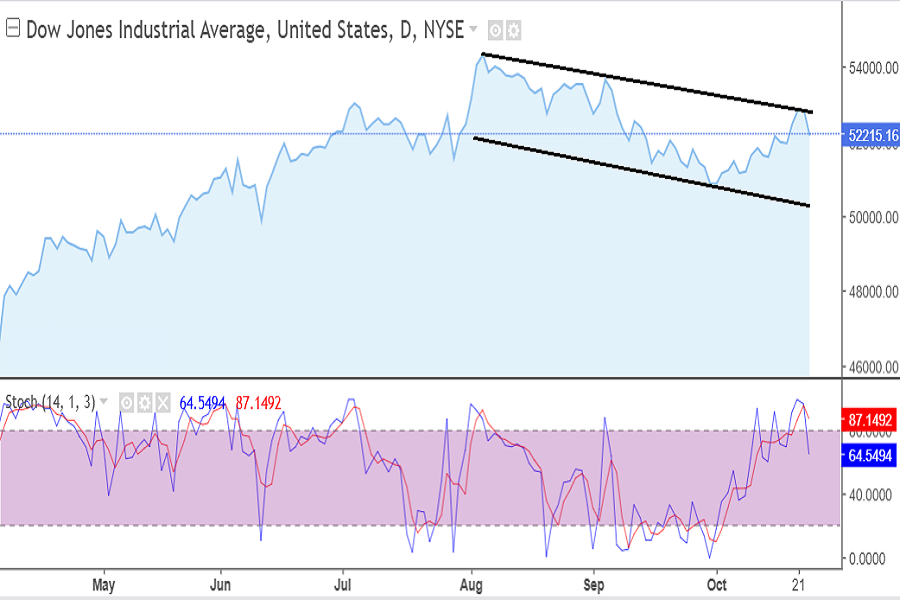
The Dow Jones index performed the best this week; however, the trend remains downward. The stochastic oscillator points to an overbought zone, which is another reason to expect the index to decline in the near term. Technical analysis indicators are providing conflicting signals.
3. Nasdaq 100 index
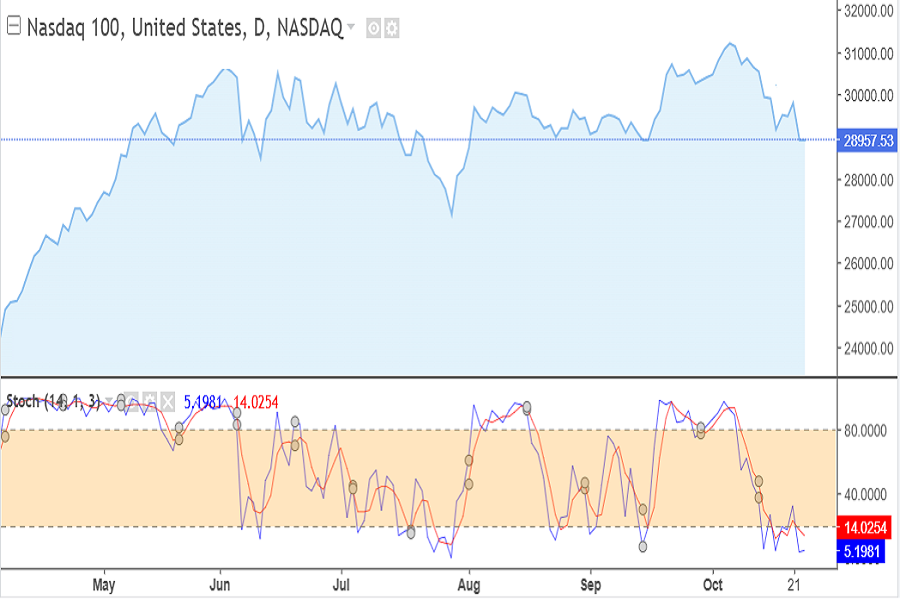
The Nasdaq index appears to be undergoing a significant price correction in October. Until recently, the technology sector had remained an island of stability. We believe, however, that the correction is now drawing to a close, and we may see a recovery in November. Nevertheless, technical analysis indicators remain pointed downward, even though the index is in oversold territory.
Key currencies outlook in the third week of October 2026
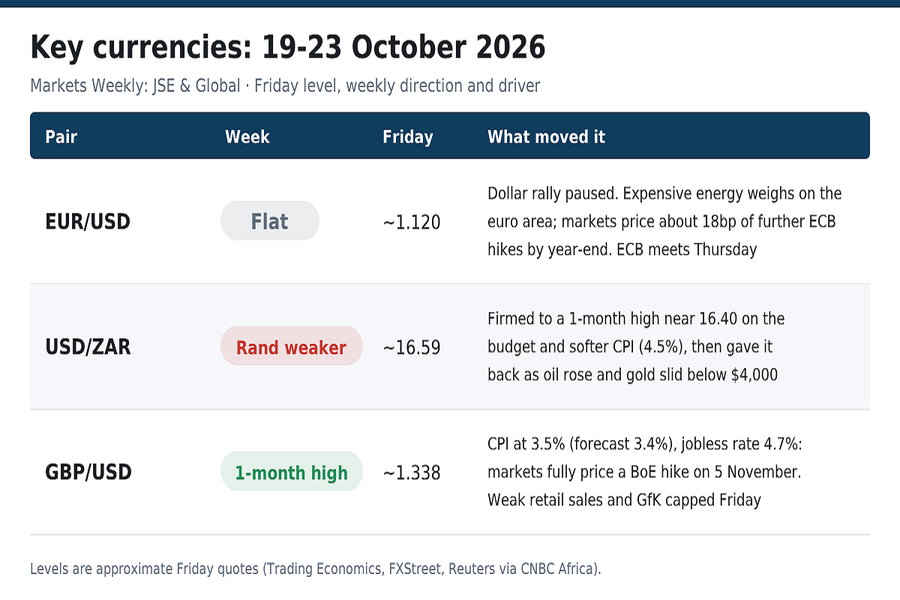
EUR/USD
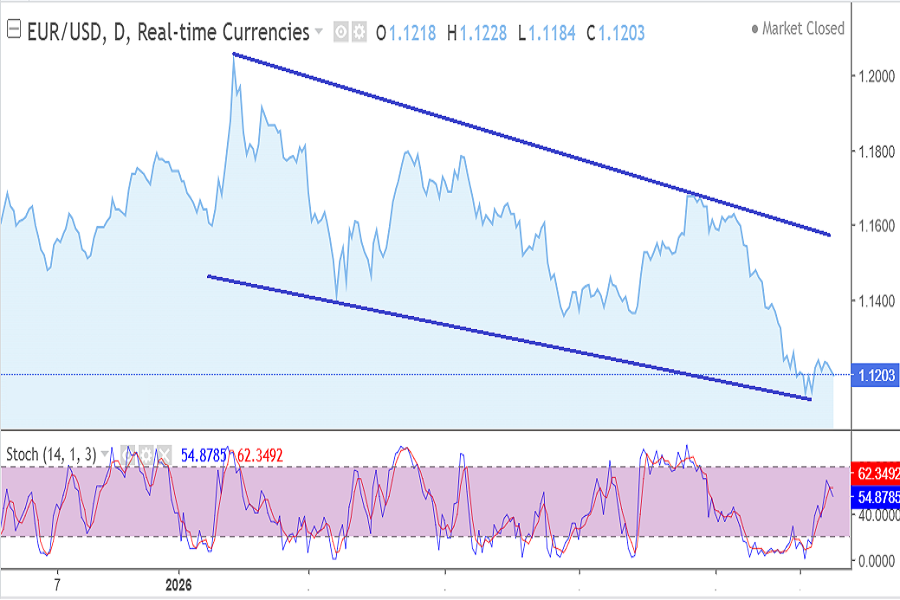
We were expecting an upward wave, but it seems the U.S. currency is not ready to yield. Instead, we have seen a period of complete consolidation, and the dollar could potentially strengthen further if the benchmark interest rate is raised. The situation might shift in November with the elections - an event that typically increases market volatility, especially if there is a change in the political landscape.
Tech indicators show us Strong sell signal which translated as - "No any way but downward". We'll see in the future.
2. USD/ZAR
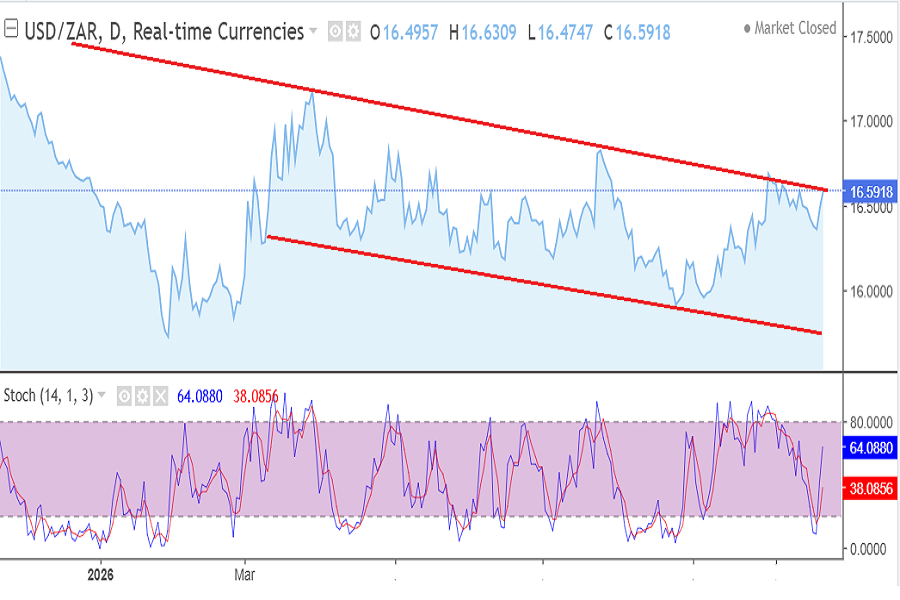
USD/ZAR had a week of two halves. On Wednesday the rand reached a one-month high near R16.40 per dollar, supported by the mid-term budget, which revised deficit and debt estimates lower, and by September inflation of 4.5%, below the expected 4.7%. From Thursday the rand gave it all back as oil climbed and gold and platinum group metals fell, ending the week near R16.59. The budget also cut the 2026 growth forecast to 1.2% from 1.6%.
On the chart, we can still see the old downward trend, but the resistance line is being constantly tested. Should oil prices continue to rise while gold prices fall, the trend will shift in favor of the rand as early as the beginning of November. Tech indicators tell us: - "Be ready", showing us Strong Buy signal and there's nothing to say against it.
3. GBP/USD
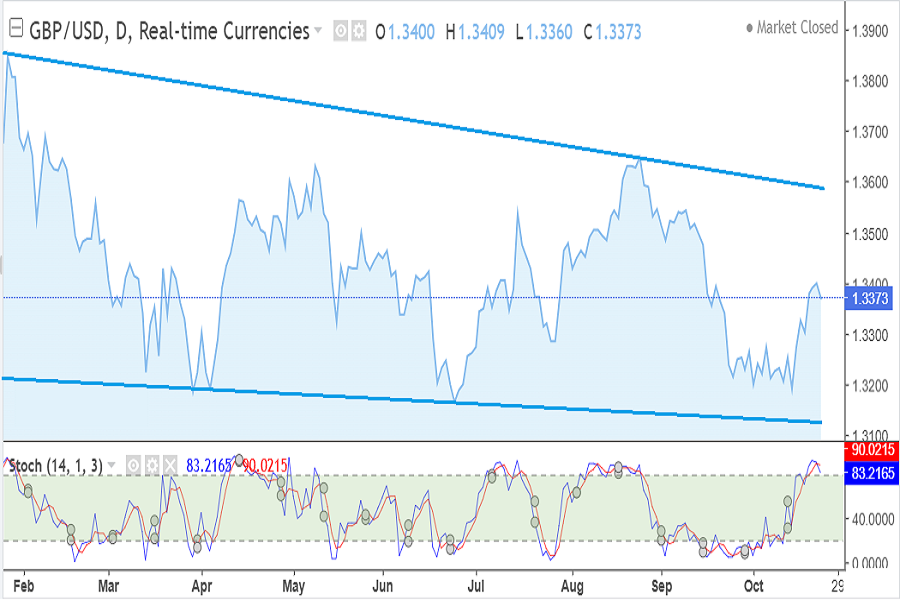
This currency pair has experienced an upward wave and is now preparing to decline, in line with its downward trend. The stochastic oscillator has reached the overbought zone, confirming that an exit from this state is inevitable. The other technical analysis indicators point the other way, signaling a buy. It is up to you to decide which outcome is more likely in the current situation.
Outro
This week was quite hard for the stock market without exceptions. All negative factors are united and impacted strong.
Next week, the Federal Reserve will make a decision regarding interest rates. While forecasts suggest they will remain unchanged this time, any announced plans could fundamentally alter the stock market. Volatility is likely to increase considering released important corporate reports in the USA and macroeconomic reports.
For South African investors, the verdict of the week is simple: as long as oil stays above $100, the rand and SA Inc remain under pressure, and Sasol remains the market’s main hedge.

Stan Lytynsky
Stan Lytynsky is a well known financial expert with more than 1000 of market reviews. For the last 10 years he wrote reviews for different blogs and websites. In particular he worked for SuperForex and Zetradex forex brokers as a market analyst. Currently he is living in Canada and focused on the African market as the most promising and growing.
Comments
Loading comments…
Log in or sign up free to join the discussion.