StockTalk Retrospective. Argent Industrial ltd: the ART of endless rise on the JSE

You won’t find this company in the daily or monthly market rally headlines; yet, its shares have risen 47% in value over the past 12 months, and investors regard it as a "safe haven."
Argent Industrial Limited (JSE: ART) boasts not only a history spanning over 50 years but also one of the most attractive stock tickers: #ART. Furthermore, the stock displays a near-perfect upward trend - smooth, with no significant pullbacks or volatile swings. The company is also led directly by its founder, Teunis Scharrighuisen, who serves as Chairman of the Board alongside a CEO with over 29 years of tenure - a factor that further bolsters confidence in the leadership.
Argent Industrial's full story of success
Argent Industrial’s roots go back to 1972, when the Scharrighuisen family moved from the Netherlands to South Africa to undertake contract earthworks, marking the inception of the Scharrighuisen Group. As the business grew, the family identified broader opportunities within the industrial sector and began to diversify.
In 1993, the group was incorporated as Scharrig Industrial Holdings (Pty) Ltd (Reg. No. 1993/002054/06) to consolidate industrial assets previously held by Scharrighuisen Holdings Limited. The company listed on the JSE on November 24, 1994, and later adopted the name "Argent Industrial Limited."
Historically, the business was centered on steel, with trading and processing accounting for the majority of revenue. From the mid-2010s, the company began a systematic shift toward manufacturing branded consumer and industrial goods; from 2017 onwards (though the process began earlier), it officially pursued a strategy of international expansion.
Over the decades, an aggressive mergers and acquisitions (M&A) strategy transformed the company into a diversified group. Today, Argent comprises over 24 companies operating not only in South Africa but also in the UK and the USA, with a workforce exceeding 1,200 employees. Thus, investing in Argent Industrial Limited is akin to investing in an entire index or ETF - an approach that appeals to proponents of such instruments due to the inherent diversification.
Argent's ART of endless growth
Despite its relatively small market capitalization (currently around R 2.17 billion), the stock has historically attracted value investors focused on dividends and tangible assets.
Since its listing, the company's share price has moved from 81 cents in 1999 to 4,190 on August 25, 2026. Thus, over 27 years on the stock exchange, the company has achieved a return of 5,170%, not to mention the dividends paid out during that period.
Throughout its time on the market, the company has endeavored to pay dividends regularly, even during periods when it reported losses. Only in 2021 was the decision made to forgo dividend payments in favor of a share buyback program.
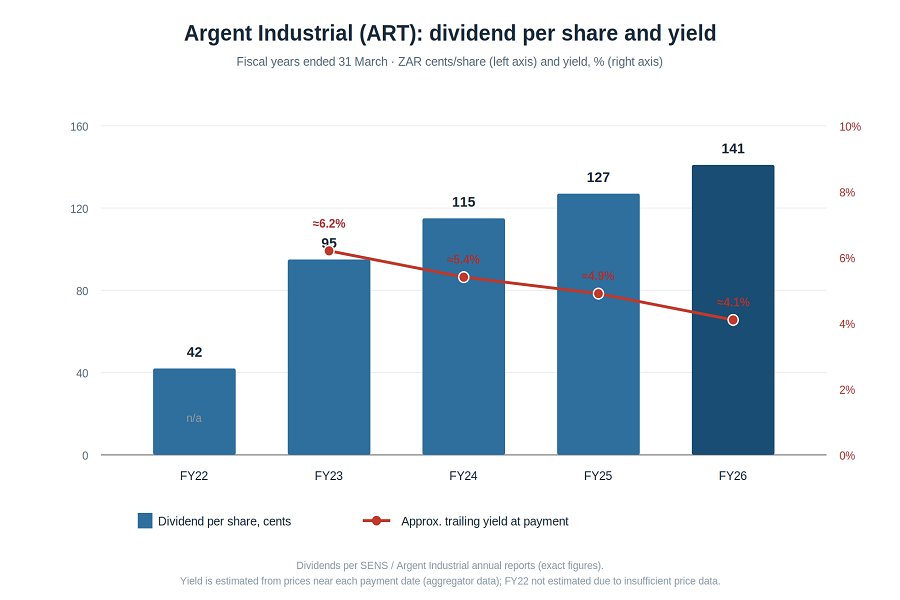
Argent Industrial dividend history for the last 5 years
Most challenging periods in its history
There're 3 problematic periods which company had to deal with:
- The Global Financial Crisis (2008–2009): This period dealt a devastating blow to the company’s metals division and steel mills. A slowdown in construction activity in South Africa and a collapse in global steel prices led to a sharp decline in profitability.
- 2014: A year that saw the company post a loss amidst the nationwide NUMSA strike in South Africa’s metals and engineering sector.
- The COVID-19 pandemic (2020–2021): Supply chain disruptions and lockdowns forced management to shift into a strict capital preservation mode. In 2021, the company made an unpopular yet strategically sound decision: to completely suspend dividend payments. Instead, all excess free cash flow was directed toward an aggressive share buyback program, which ultimately laid the foundation for explosive share price growth in the years that followed.
Argent Industrial Today
Today, Argent Industrial is not merely a South African steel distributor but a vertically integrated international business. Its operations are divided into three key segments:
- Manufacturing: Production of a wide range of products—from security systems (the Xpanda brand) and fireplaces (Jetmaster) to specialized equipment (American Shutters, Hendor).
- Steel Trading: Supply of ferrous metals, aluminum, and stainless steel with value-added services (through Phoenix Steel and Gammid).
- Properties: Ownership of key real estate assets that house the company’s manufacturing facilities.
Particular attention should be paid to international expansion. Operations in the UK (Cannock Gates, Fuel Proof) and North America generate substantial foreign currency revenue for the company, serving as an excellent hedge against South African rand volatility.
Latest financial report show us gradual increase with all metrics, This of course positively affecting on the stocks value.
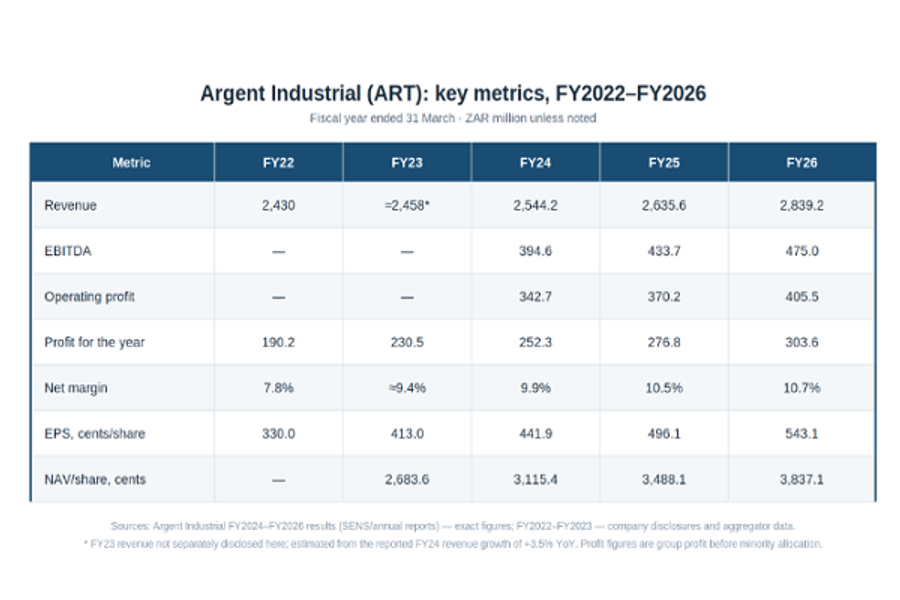
Argent Industrial (JSE: ART) key metrics 2022-2026
Argent demonstrates exemplary financial health based on recent reports. The company trades at a P/E ratio of approximately 7.5. This is a highly attractive valuation—with a multiple below the market average, indicating that the company remains undervalued despite the rise in its share price.
Notably, #ART shares have grown by an average of 32% annually over the past three years, outpacing the growth rate of earnings itself (approximately 9–10% per year). This reflects investors' high regard for the quality of the business.
After a pause in 2021, the company resumed dividend payments and has demonstrated steady annual growth. Its capital allocation strategy is quite conservative; the payout ratio remains at a comfortable level of around 24–26%, leaving significant headroom for future increases.
Technical Analysis for Argent Industrial - short review
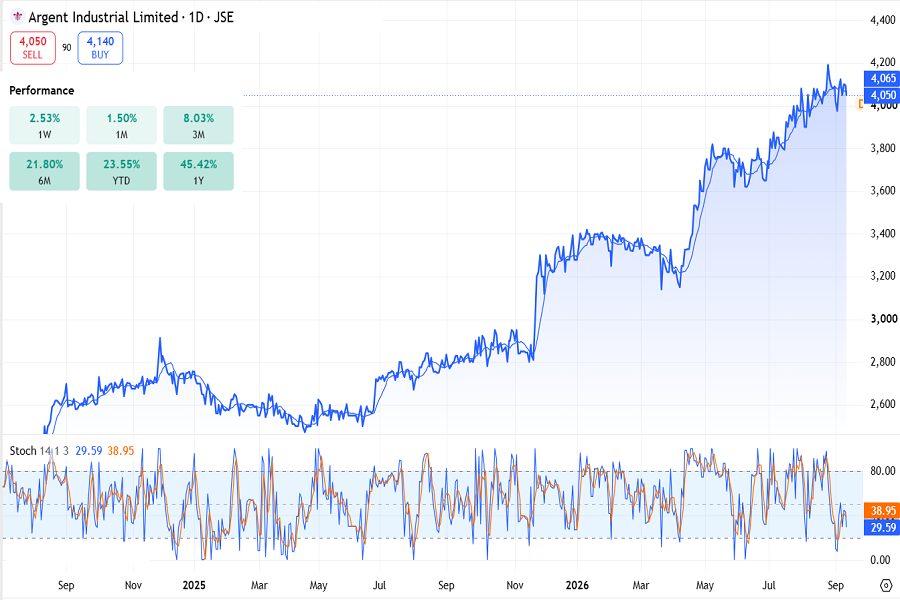
Argent Industrial ltd stocks on the JSE, September 2026
The chart shows an upward trend spanning six years - a rare sight in the market. Over the past 12 months, the stock has risen by 45% and recently tested its highs. What do analysts say? The stock deserves better. Technical analysis indicators are neutral. Oscillators signal a potential price correction, reacting to high price levels and a slowdown in the trend.
Forecast for Argent Industrial Limited (Outlook)
The outlook for ART shares remains moderately positive, with a focus on a "Hold" rating (or "Buy" for value investors).
- Growth drivers: Further expansion into the US and UK, steady demand for security systems in South Africa, and a consistent share buyback policy that boosts EPS.
- Risks: Argent’s primary vulnerabilities are its micro-cap status and low market liquidity. Additionally, the commodities-related nature of part of its business makes the holding company sensitive to global steel price cycles and potential logistical disruptions.
Bull Case
- International expansion and currency hedging: Over 40% of the Group’s operating profit is already generated outside South Africa—primarily in the UK (Fuel Proof, Cannock Gates) and the US. Continued sales growth in developed markets hedges the company against South African rand (ZAR) devaluation and reduces reliance on the local South African economy.
- The "magic" of share buybacks: Argent’s management systematically repurchases and retires its own shares when market valuations are low. This artificially reduces the total share count and boosts earnings per share (EPS), even when overall revenue growth is modest.
- Valuation discount (Multiple expansion): With a current P/E ratio of ~7.5x, the company trades at a significant discount to its international industrial peers. Any market re-rating toward industry-average P/E levels (11–13x) would provide a strong boost to the share price.
- Room for dividend growth: With a payout ratio of just ~24–26% of net profit, the company’s dividend policy remains highly conservative. The business has significant headroom for double-digit annual dividend increases or special dividend distributions, provided there are no major M&A deals.
🐻 Bear Case
- Small-Cap Discount: With a market capitalization of approximately R2.17 billion, ART falls into the micro-cap category, characterized by low liquidity on the JSE. Large institutional funds are often unable to invest in such stocks due to investment limits, creating a risk that the shares remain trapped in a state of undervaluation for an extended period.
- Commodity Cycle Sensitivity: A portion of the holding company’s business is tied to steel trading (Phoenix Steel, Gammid). A drop in global ferrous metal prices or a sharp contraction in demand within South Africa’s construction sector immediately impacts the margins of the Steel Trading segment.
- South African Infrastructure Constraints: Issues with port and rail logistics managed by state-owned operators (specifically Transnet) and power supply disruptions in South Africa can drive up operating costs and cause delivery delays for the group's manufacturing divisions.
- M&A Integration Risks: The group’s growth model relies heavily on acquiring smaller overseas manufacturers. Errors in valuing target companies or difficulties during integration could strain the balance sheet and divert free cash flow.
Summary
Compared to many other listed companies, Argent Industrial Limited stands out like a gem: a six-year rally, consistent dividend payouts even during loss-making periods, a share buyback program, and a business that is both geographically and structurally diversified. The list of arguments in favor of this asset is extensive.
It is, perhaps, a "boring" business - in the best sense of the word. It lacks the hype surrounding tech startups but boasts real manufacturing facilities, stable cash flow, growing dividends, and competent management capable of generating profits in both crisis conditions and bull markets. Yet, is it wise to buy shares at their highs, without a discount? This may well be the exception to the rule worth making, given the stock's long-term price chart, which shows no significant drawdowns or periods of deep discounting. Each investor must decide this for themselves by weighing the arguments for and against Argent Industrial Limited.

Stan Lytynsky
Stan Lytynsky is a well known financial expert with more than 1000 of market reviews. For the last 10 years he wrote reviews for different blogs and websites. In particular he worked for SuperForex and Zetradex forex brokers as a market analyst. Currently he is living in Canada and focused on the African market as the most promising and growing.
Comments
Loading comments…
Log in or sign up free to join the discussion.