JSE & Global Markets for the third week of September 2026

This week was the most highly anticipated one for global stock markets. Investors were eager to gain clarity on central bank monetary policy and the near-term macroeconomic outlook. The Federal Reserve's headline move came as no surprise—a 25bp hike, its first since 2023, had been well flagged since Chair Warsh's hawkish Jackson Hole remarks in late August. The real surprise was in the details: a unanimous 12-0 vote and a markedly more hawkish dot plot, with 16 of 18 committee members now projecting at least one further hike this year, up from just 9 in June. Global indices reacted in various ways, ranging from muted to sharp responses. Unsurprisingly, the financial sector, being the most sensitive to monetary policy, took the hardest hit, while the technology sector proved the most resilient.
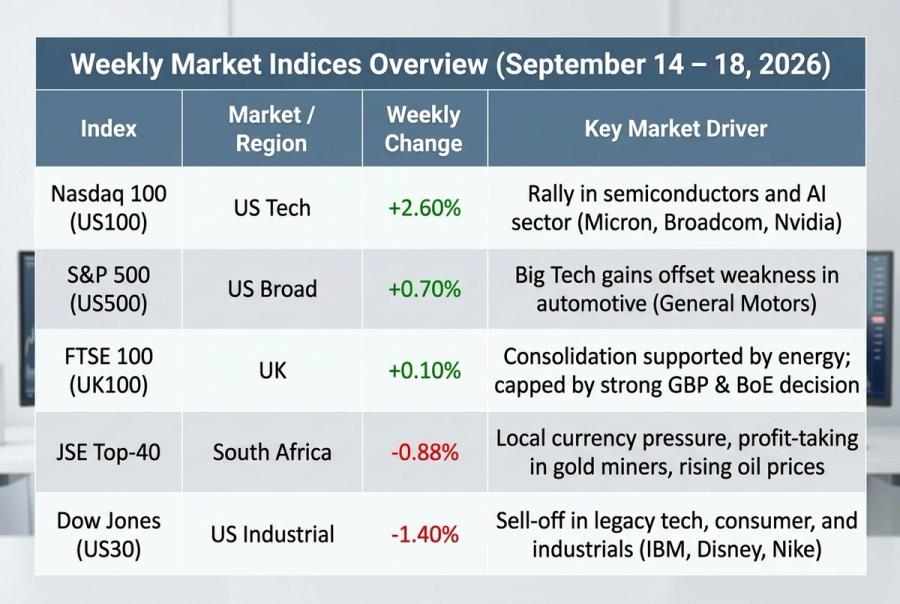
On the comparison table you can unusual situation when even within US market indices were moving in different ways, at the same time being impacted with the same factors. In this review, you will see why stock market reaction was different? We will back to this question with detailed US market review.
JSE Market – Third Week of September.
The primary external drivers for the South African stock exchange this week were the decisions made by the US Federal Reserve and the Bank of England; investors adopted a wait-and-see approach ahead of the meetings and then reacted to the regulators' subsequent commentary. Although the corporate earnings calendar was light with fewer than ten reports released, most of the results were exceptionally strong, triggering bouts of volatility in specific stocks. The mining sector remained under pressure, despite the resilience of the rand and a sharp shift in global market sentiment, moving from "risk-off" to a rapid "risk-on" rally following the Fed's decision. The week's real surprise, however, was the commercial education sector, represented on the JSE, which attracted heightened investor interest and demonstrated strong momentum.
Stadio Holdings (JSE: SDO) stocks increased in price by 42%, taken 4 trading days of 5 with steady growth. Investors likely remembered about their strong report which show 10% increase in number of students and 13% growth in revenue. The unexpected rally in the company's shares came as a complete surprise, given that firms in this sector typically fly under the radar. However, it demonstrates that amidst geopolitical and macroeconomic turbulence, investors are seeking assets less vulnerable to external factors, especially as the cost of education, and the demand for it, continue to rise.
The strongest financial report on the JSE has been published by the Golden mining company - Pan African Resources. The company was evidently reporting on the most successful period for gold miners - a time when gold prices were at their peak.
According to the report their dividends increased by 108%, earnings per share increased by 199.5%, profit is up by +153%. Of course nobody manage to show something better this week and even this month.
UK Stock Market on the middle of September
The British stock market, recently under pressure due to a stagnant mining sector, was bolstered this time by a strong macroeconomic backdrop. First, the Bank of England announced it was keeping the benchmark interest rate unchanged at 3.75%; second, unemployment data remain below forecast of 5.0% at the level of 4.9%. Investors did not see explosive growth in the index; instead, it closed virtually flat, effectively holding the ground it had previously gained.
Of course, this did not prevent some companies from ending the week with impressive success. Kier Group (LSE: KIE) stocks increased in price by 29% this week. This was made possible by a strong report published on September 15. According to the report, For the first time in over 10 years, the company ended the year with a net cash position. They also show Record order book of £11.9 billion (+8% year-on-year), covering over 90% of FY27 revenue. Earnings per share increased by 8.8% and revenue - by 7.5%.
Who is Kier Group? - A British infrastructure and construction group that carries out major projects, such as the construction of bridges, roads, and railways. So the state is its primary client. In 2026 their stocks added 40% and Septemmber is currently their best month.
US Market in the middle of September 2026
As previously mentioned, the US market clearly shifted over the course of the week in response to the Federal Reserve meeting. Investors took particular note of the fact that the decision to raise interest rates was unanimous. Furthermore, 16 out of 18 officials projected another rate hike before the end of the year. Rather than offering reassurance, this hawkish signal initially unsettled markets, triggering a sharp Wednesday selloff as Treasury yields pushed above 5% for the first time since 2007. A rebound followed the next session, led largely by technology, though this owed more to an oversold bounce and sector-specific positives than to renewed confidence in the Fed's path. Nevertheless, the financial sector came under the greatest pressure throughout, leaving little room for the companies of the US30 index to recover.
The most successful stocks of course they have this week as well.
Schrodinger, Inc. (NASDAQ: SDGR) stocks listed on NASDAQ increased in price by 52%. Developer of a "physics+AI" platform for the computer modeling of molecules, used in drug and materials development, announced that they open affiliated biotech company, Tectora, in cooperation with top-tier venture capital firms New Enterprise Associates (NEA) and RA Capital Management.
For the market, this signals that companies are prepared to monetize their platforms through spin-outs involving major investors: indirect confirmation of the Schrodinger technology's value.
Pershing Square Inc. (NYSE: PS) is a winner of the week on NYSE, with growth of 31%.
Bill Ackman’s management company, which trades separately from his closed-end fund Pershing Square USA, jumped in value based on raised price targets from analysts and rumours on reinvesting dividends by dedicated investors. This is taking place against the backdrop of company management promoting the argument that the shares are absurdly undervalued on the stock market.
Skeptics, on the contrary, argue that the company's high share price is based solely on the founder's reputation, rather than the asset's actual value or the figures in the reports. By the way, Bill Ackman (William Albert Ackman) is an American billionaire, well known activist investor, and the founder and CEO of the investment firm Pershing Square Capital Management.
Enova International (NYSE: ENVA) with -22.6% can be called a crash of the wek on the US market. They're fintech company, so related to the financial sector for which this week was hard.
As for this particular Company their stocks have fallen by price due to withdrawal of regulatory applications required to complete the acquisition of Grasshopper Bancorp. Seems like the deal has been cancelled although It was announced back in December 2025 and was set to grant Enova the status of a bank holding company for the first time.
The market reaction was immediate and severe: the stock opened on Tuesday, September 15, with a 22.27% downward gap - even before the announcement of a US interest rate hike.
CEO Steve Cunningham attributed the withdrawal of the applications to uncertainty regarding regulatory standards for non-financial companies seeking bank status, stating that the approval process is subject to political pressure and external lobbying.
Key indices technical overview
JSE TOP-40 index
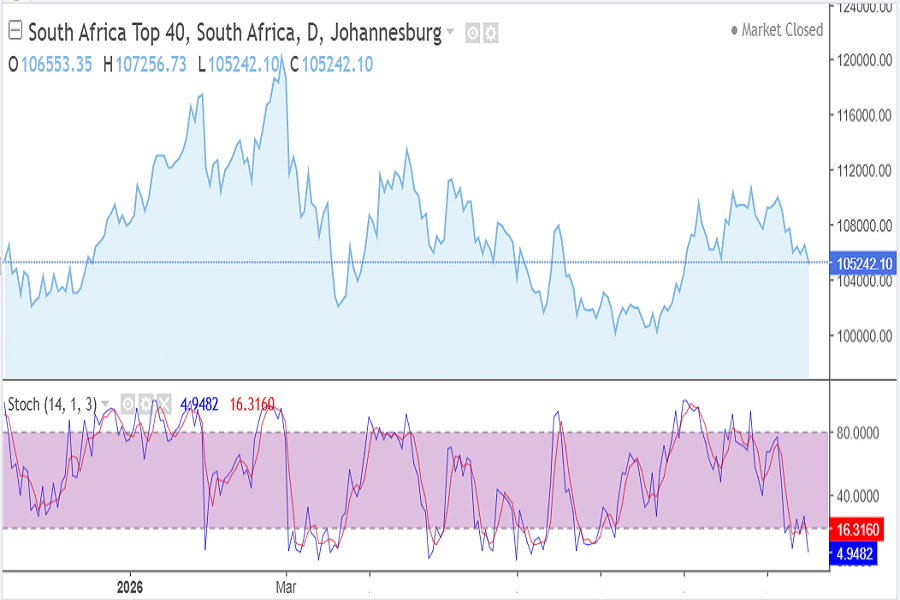
TOP-40 JSE index, September 14-18, 2026
September proved to be a challenging month for the companies included in the index, though it must be said that they weathered the past week reasonably well. The decline continued, albeit by less than one percent.
Nevertheless, the price correction persists. Share prices have already entered oversold territory. A month ago, one could confidently speak of a trend reversal to the upside, but that upward momentum was lost long ago. Technical analysis indicators are signaling a sell, and this assessment may well be correct.
2. UK100 index in the middle of September
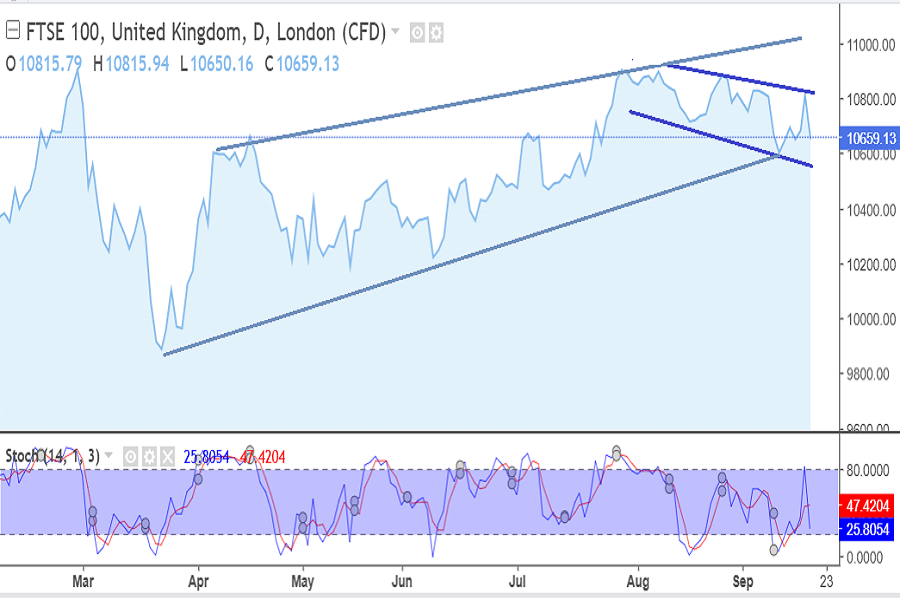
UK100 index, September 14-18, 2026
The rates remain within an upward trend but are undergoing a price correction. The decline is slowing, as the index is ending its second week with virtually no movement.
Tech indicators show Strong sell signal. We believe downward momentum continue at least for the next few weeks.
3. S&P500 US index tech analysis
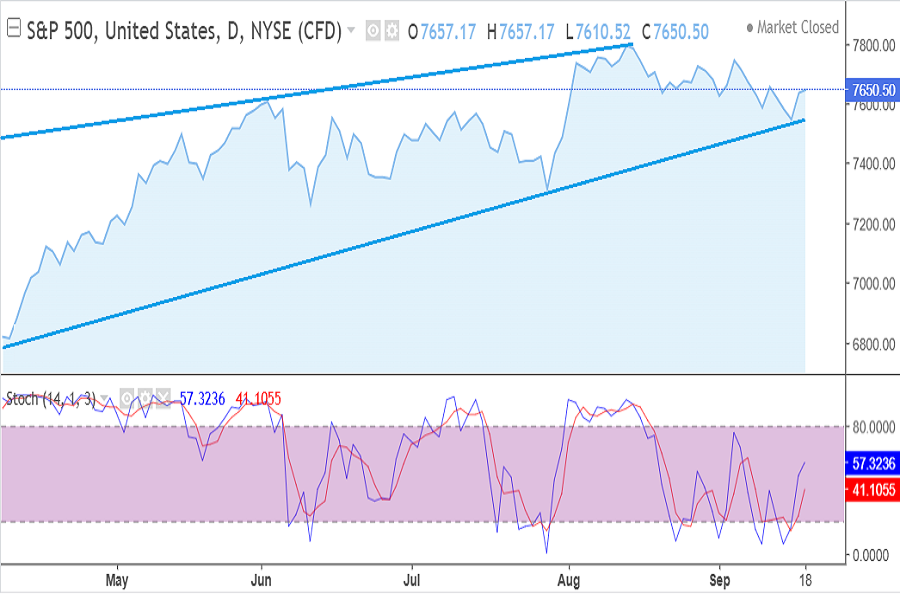
S&P500 index September 14-18 2026
The upward trend remains unquestionable for now. Prices are currently undergoing a correction, though it may be nearing its end. Even during what is typically the toughest week of September for the US stock market, the index demonstrated strength by closing in positive territory.
Technical indicators are showing mixed signals on the daily timeframe. This, in turn, suggests a potential shift of the indicators back into positive territory, making this an interesting entry point to consider.
4. US30 index (Dow Jones)
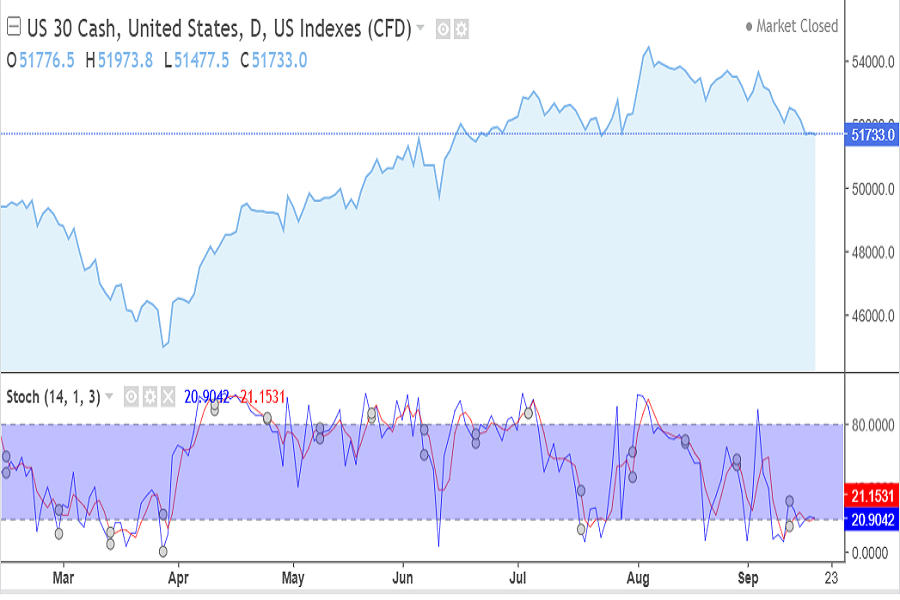
US30 index, September 14-18, 2026
The US30 index suffered the sharpest decline among the major indices this week, dropping to levels not seen in two months. This occurred because a significant number of the companies comprising the index belong to the financial and banking sectors, which do not benefit from rising interest rates.
If the index continues to lose 1.6% over the next few weeks, we can confidently speak of a trend reversal. For now, we simply note another bad week for the index and bearish signals from technical analysis indicators.
5. NASDAQ 100 index technical analysis
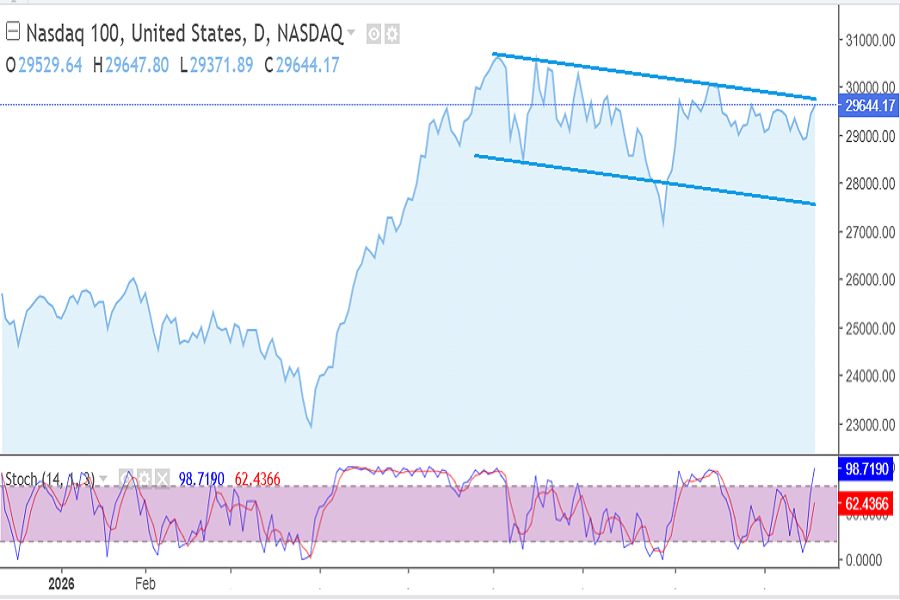
Nasdaq100 index September 14-18, 2026
Unlike other indices, the Nasdaq 100 is showing a downward trend—the opposite of the situation with the US30. It was an excellent week for the index; despite mixed signals throughout the week, the technology sector drove it up by more than 2.5%. Nevertheless, this remains entirely consistent with the downward trend. We may be looking at the start of a price correction, but nothing more than that.
Technical analysis indicators are pointing to a buy signal. If the index can handle a week like this, it has the potential to surge toward its highs during a calmer, more favorable period.
Key currency pairs for the third week of September 2026
EUR/USD technical review
Both central banks raised rates in September (the ECB on September 10, to 2.50%), but the Fed’s hawkish surprise widened the rate gap more than expected. In addition to monetary policy, the record yields on US government bonds are undoubtedly sustaining interest in the dollar, and many view it as a safe-haven asset. This way the USD was stronger this week.
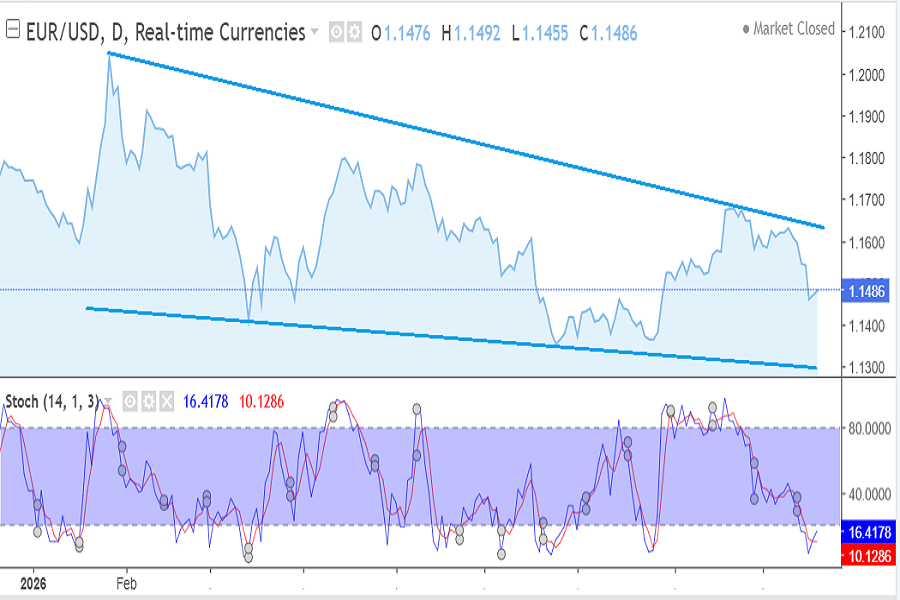
EUR/USD in September 14-18 2026
On the chart it looks like the end of strong price correction. In this case you expect further decrease next week and have all chances to see it in fact. Moreover such expectations are supported with tech indicators that show us Strong Sell signal. At the same Stochastic oscilator identified the rates in the oversold zone.
Next week will be much stable. USD can still be supported with published Manufacturing PMI indices and updated data on labour market.
2. USD/ZAR tech review
As expected, the rand retreated amid strong dollar support, and the same could happen to the rand itself next week. The South African Reserve Bank is set to meet on Wednesday, and the currency could receive a boost if the benchmark interest rate is raised or other hawkish signals are issued.
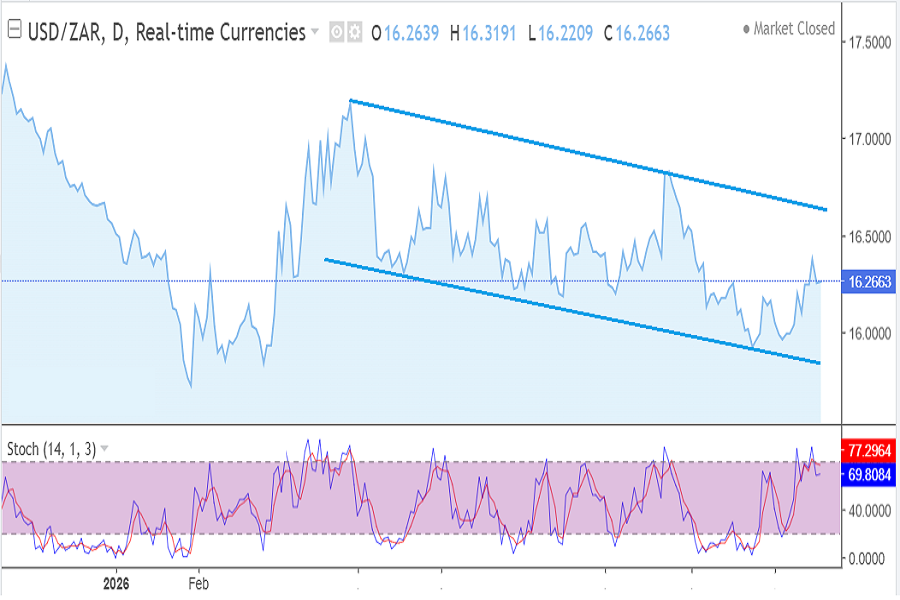
USD/ZAR September 14-18, 2026
The trajectory of the price chart leaves no room for doubt. The downward movement may well continue in the very near future. Technical analysis indicators appear confused, yet from the perspective of the same technical analysis, we see no other forecast than a continued decline in line with the trend.
JSE & Global markets for the third week of September: Summary
Thus, the week was shaped less by a single event than by two central bank decisions: the Federal Reserve's hawkish hike set the tone for global markets, strengthening the US currency and weighing hardest on the financial sector, while the Bank of England's hold offered UK equities a partial counterweight. Geopolitical risk, chiefly the US-Iran tensions keeping oil above $100 a barrel, remained an active undercurrent rather than fading into the background, continuing to feed the very inflation pressures both central banks are now grappling with. The coming week may bring less noise for most markets, though not for all of them: South Africa's Reserve Bank still has its own rate decision to deliver, on 23 September.

Stan Lytynsky
Stan Lytynsky is a well known financial expert with more than 1000 of market reviews. For the last 10 years he wrote reviews for different blogs and websites. In particular he worked for SuperForex and Zetradex forex brokers as a market analyst. Currently he is living in Canada and focused on the African market as the most promising and growing.
Comments
Loading comments…
Log in or sign up free to join the discussion.